Britain's Betting Evolution: Tracking Shifts in Wagering Trends and Market Dynamics
Xander Jenkins · Oct 17, 2026
UK Gambling Operators Signal Risks from Upcoming Budget Tax Proposals
Two prominent UK gambling companies delivered a direct message to Chancellor John Healey on October 15 2026 regarding the Budget set for October 28 and the possibility of further tax adjustments that could affect their retail networks. Entain which operates Ladbrokes and Coral along with Rank Group the parent of Grosvenor Casinos and Mecca Bingo outlined how additional duty increases might accelerate venue closures and reduce employment levels in the sector. Observers note that these communications arrived even as both firms reported positive revenue movements in their domestic operations during the most recent quarter.
Details of the Industry Warnings
Company representatives referenced earlier rounds of tax changes that produced more than 600 betting shop closures and over 10 250 job reductions across the industry. They explained that similar measures in the forthcoming Budget could compound those effects by pressuring margins at physical locations where costs have already risen. The statements positioned the warnings as forward-looking assessments based on current trading patterns and projected fiscal shifts rather than immediate operational announcements.
Revenue Performance Amid Broader Context
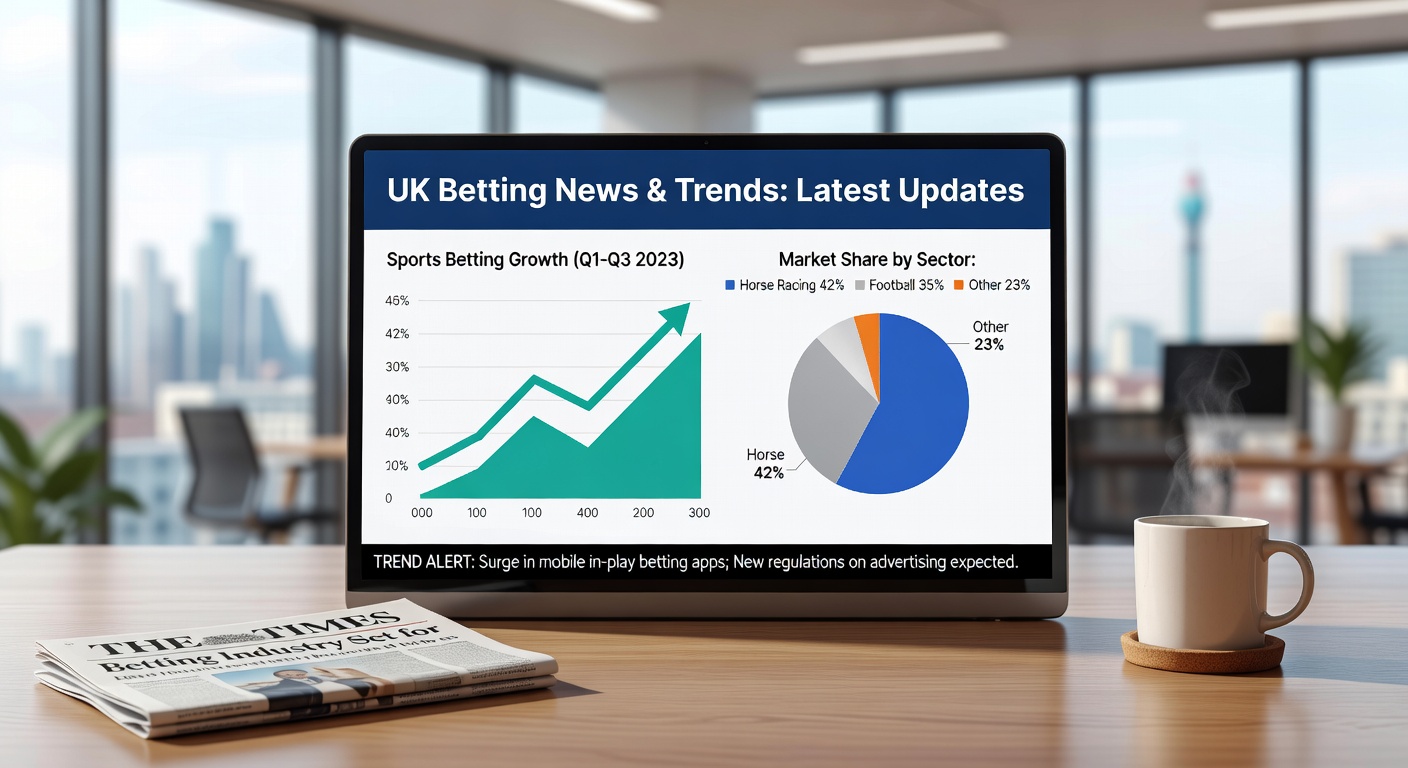
Entain recorded a 2 percent increase in third-quarter net gaming revenue across its UK and Ireland activities with online channels contributing an 8 percent rise driven largely by a 14 percent advance in digital betting. Rank Group meanwhile posted a 5 percent like-for-like net gaming revenue gain during the comparable period. These figures emerged despite the companies highlighting structural challenges in their high-street portfolios. Data from industry monitoring groups shows that online segments have continued to expand while retail venues face sustained pressure from changing consumer habits and regulatory requirements.
Those who've followed fiscal policy in this area point out that duty rates on gaming machines and betting activities have undergone multiple revisions since 2014. Each adjustment produced measurable shifts in venue economics according to internal company analyses shared with government officials. The current exchange between operators and the Treasury reflects ongoing dialogue about how tax structures interact with investment decisions and employment levels in both urban and regional markets.
Historical Precedents and Sector Responses
Previous tax increases prompted widespread reviews of shop portfolios with operators closing locations where footfall and margins no longer supported continued operation. Rank Group and Entain have both adjusted their physical footprints in recent years while directing resources toward digital platforms that demonstrate stronger growth trajectories. Government records indicate that the Chancellor received these latest submissions alongside other submissions from trade bodies representing hospitality and leisure interests ahead of final Budget preparations.
What's notable is how the timing aligns with reported business expansion in specific segments. Online revenue growth at Entain outpaced overall figures while Rank maintained steady like-for-like gains across its casino and bingo estates. These patterns suggest that retail and remote channels respond differently to tax environments and that any uniform duty rise would affect each segment according to its cost structure and customer base.
Potential Outcomes Discussed in Communications
Company statements referenced risks to future capital expenditure plans if tax liabilities increase beyond current thresholds. They noted that reduced investment could slow refurbishment programs at remaining venues and limit expansion of newer formats. Employment considerations featured prominently with references to roles supported directly by betting shops and casinos as well as indirect positions in supply chains and local services. The communications stopped short of specifying exact numbers of additional closures and instead framed the issue in terms of cumulative pressure on an already adjusted network.
One study from an international research institute on gaming economics has examined similar tax shifts in other jurisdictions and found that retail operators often accelerate digital migration when physical margins tighten. While that analysis focused on markets outside the UK the underlying mechanics around duty sensitivity appear consistent across regulated environments. UK operators have referenced such comparative data in their submissions to illustrate potential long-term structural changes.
Conclusion
The October 15 2026 communications from Entain and Rank Group form part of a wider set of inputs reaching the Treasury before the scheduled Budget announcement. They highlight the interplay between tax policy retail viability and employment outcomes in the gambling sector at a moment when revenue trends show divergence between online and physical channels. The situation remains subject to the final decisions outlined on October 28 with further details expected to clarify the scale of any duty adjustments and their application across different gambling products.